


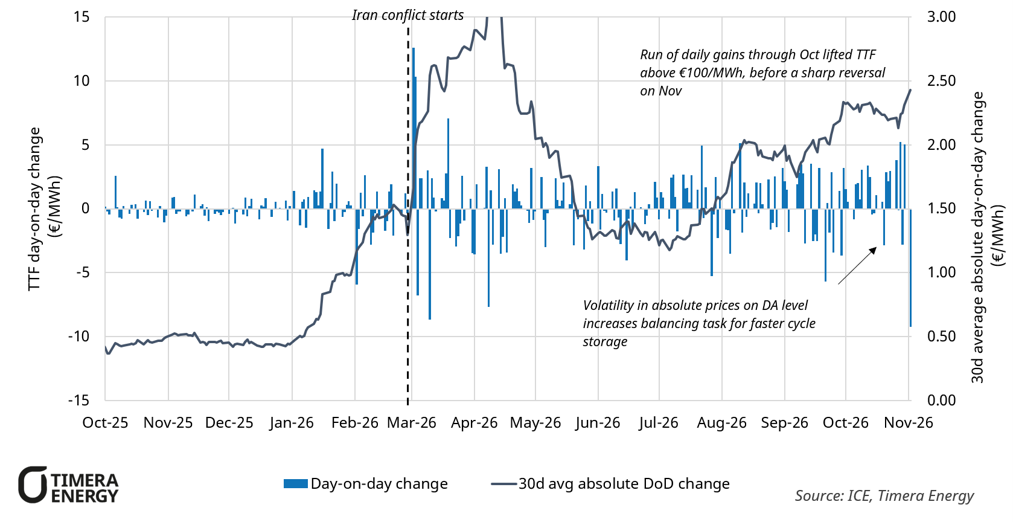
Europan gas price volatility was already building into early 2026, but the onset of the conflict in March triggered a step change. The market had to price in a significant supply loss in both Asia and Europe. Average daily moves peaked near €4/MWh across March-April, around four times last winter’s levels.
Expectations of a prolonged conflict have taken hold towards the backend of Summer-26, with no credible path to a peace deal, rebuilding volatility into prices.
With European storage refill falling short vs normal levels, there is less inventory flex. That increases reliance on LNG, with Europe needing to price cargoes away from the Pacific Basin. Europe can outcompete Asia by pricing higher to attract flexible cargoes, with the global market balancing off more inelastic Asian demand levels, which helps lift volatility higher.
This market environment is increasing the value of holding flexibility. With greater volatility around hub price movements, fast-cycle storage is well placed to optimise injection & withdrawals. Intrinsic seasonal spreads have been narrow/backwardated for much of the year, but volatility & winter upside risk are creating substantial extrinsic value for flexible assets.
For further information on our short term market views, and further analysis into value capture of flexible assets, please contact David Duncan (David.duncan@timera-energy.com)