


Latest reports suggest ARERA has approved Italy’s ‘gas liquidity service’, due to start as early as 1 January 2027 with an initial experimental phase. ARERA has signalled changes to the original proposal, though details await publication of the final text, so the summary below is based on the June consultation.
Italian scheme aims to narrow PSV-TTF spread
The service aims to compress the PSV–TTF spread by subsidising incremental imports at Passo Gries, via France (Oltingue) or Germany (Wallbach), using currently unbooked transport capacity. It is funded up to €200m, with ARERA estimating up to ~30 mcm/d (~11 bcm/yr) could be available.
Under the initial consultation, providers would be selected through a Snam-run tender, bidding both a fixed premium and a volatility fee (capped at €0.50/MWh). The premium is paid for offering daily volume into Italy at Passo Gries, whether or not the gas is ultimately delivered.
Providers must offer this volume daily in a new day-ahead auction at no more than TTF plus their volatility fee. Any revenue above that price is refunded to Snam, so providers get no benefit from PSV–TTF spikes.
Snam is due to pre-agree public terms with FluxSwiss for the Swiss leg, removing risk for bidders on this component. French or German exit and Snam entry are booked through PRISMA as normal, so providers do carry auction-premium and availability risk. The main commercial exposure though is basis: revenue is TTF-indexed but gas is sourced at THE or PEG, leaving providers effectively short those spreads.
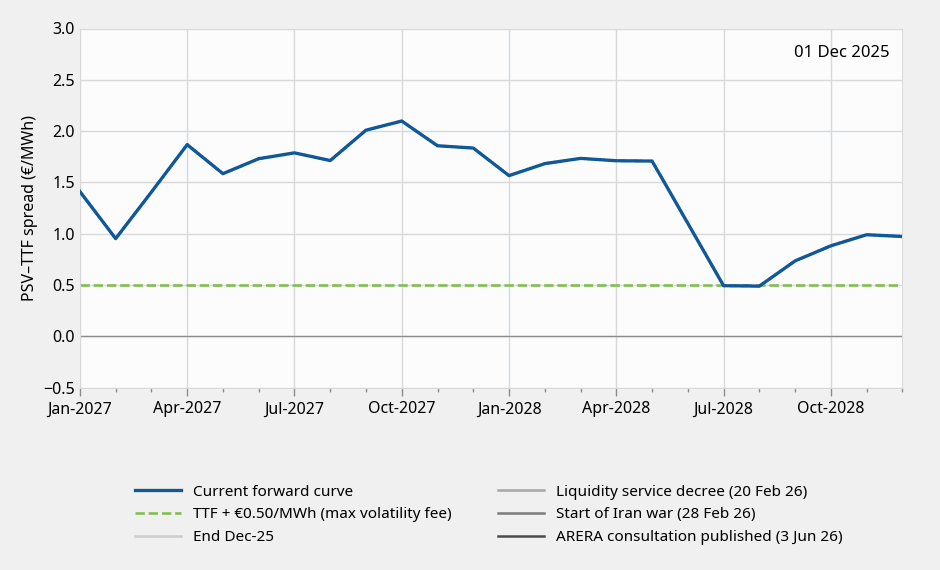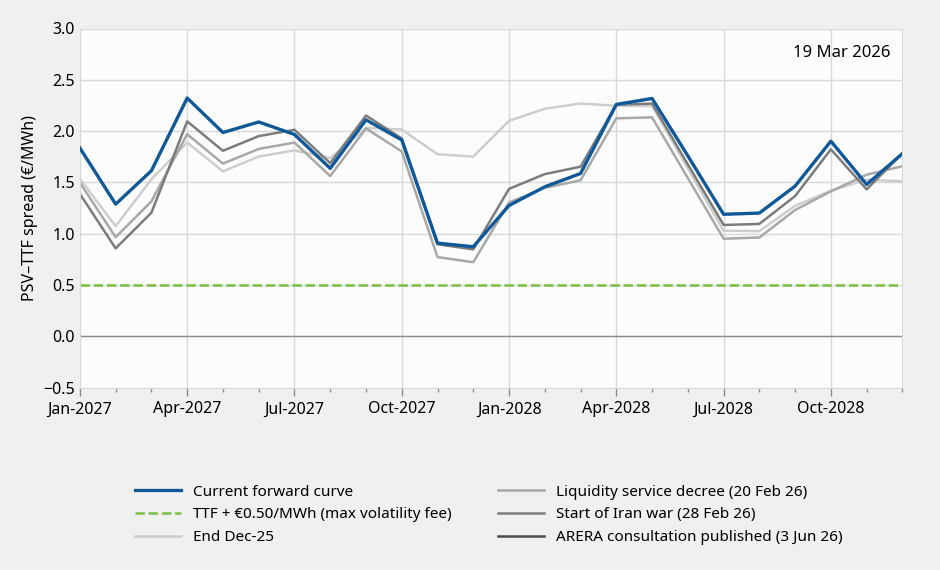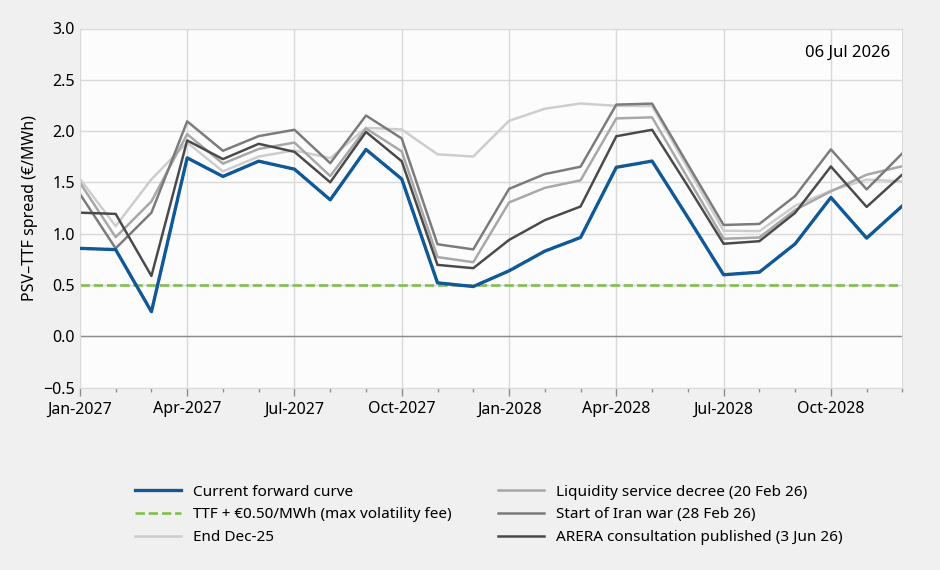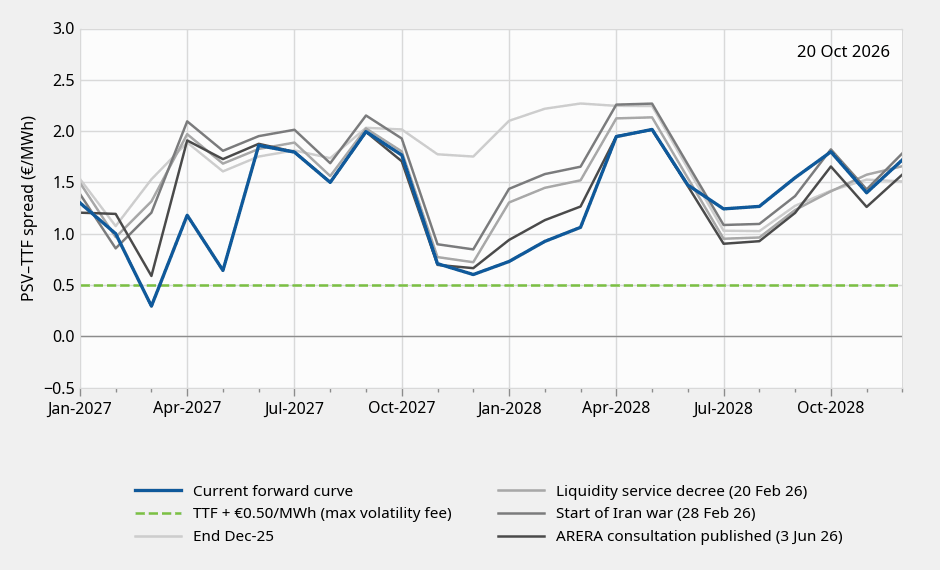
As the chart shows, the forward curve suggests limited pricing of the scheme. PSV–TTF monthly contracts average €1.25/MWh in 2027, well above the TTF + €0.50/MWh ceiling the scheme targets, and only modestly below the 2028 monthly average (€1.53/MWh), when the scheme is not currently due to run. Much of the 2027 discount reflects a weak Q1-27, driven by Italy’s stronger storage position relative to CNWE.
This suggests the market is either not yet pricing in the scheme or expects volumes to be insufficient to cover marginal gas requirements.
We’ll be publishing an in-depth analysis on the Timera Portal for Global Gas subscribers, setting out our view on the implications for PSV–TTF spreads. To discuss the report or the liquidity service in more detail, please contact Luke Cottell at luke.cottell@timera-energy.com.