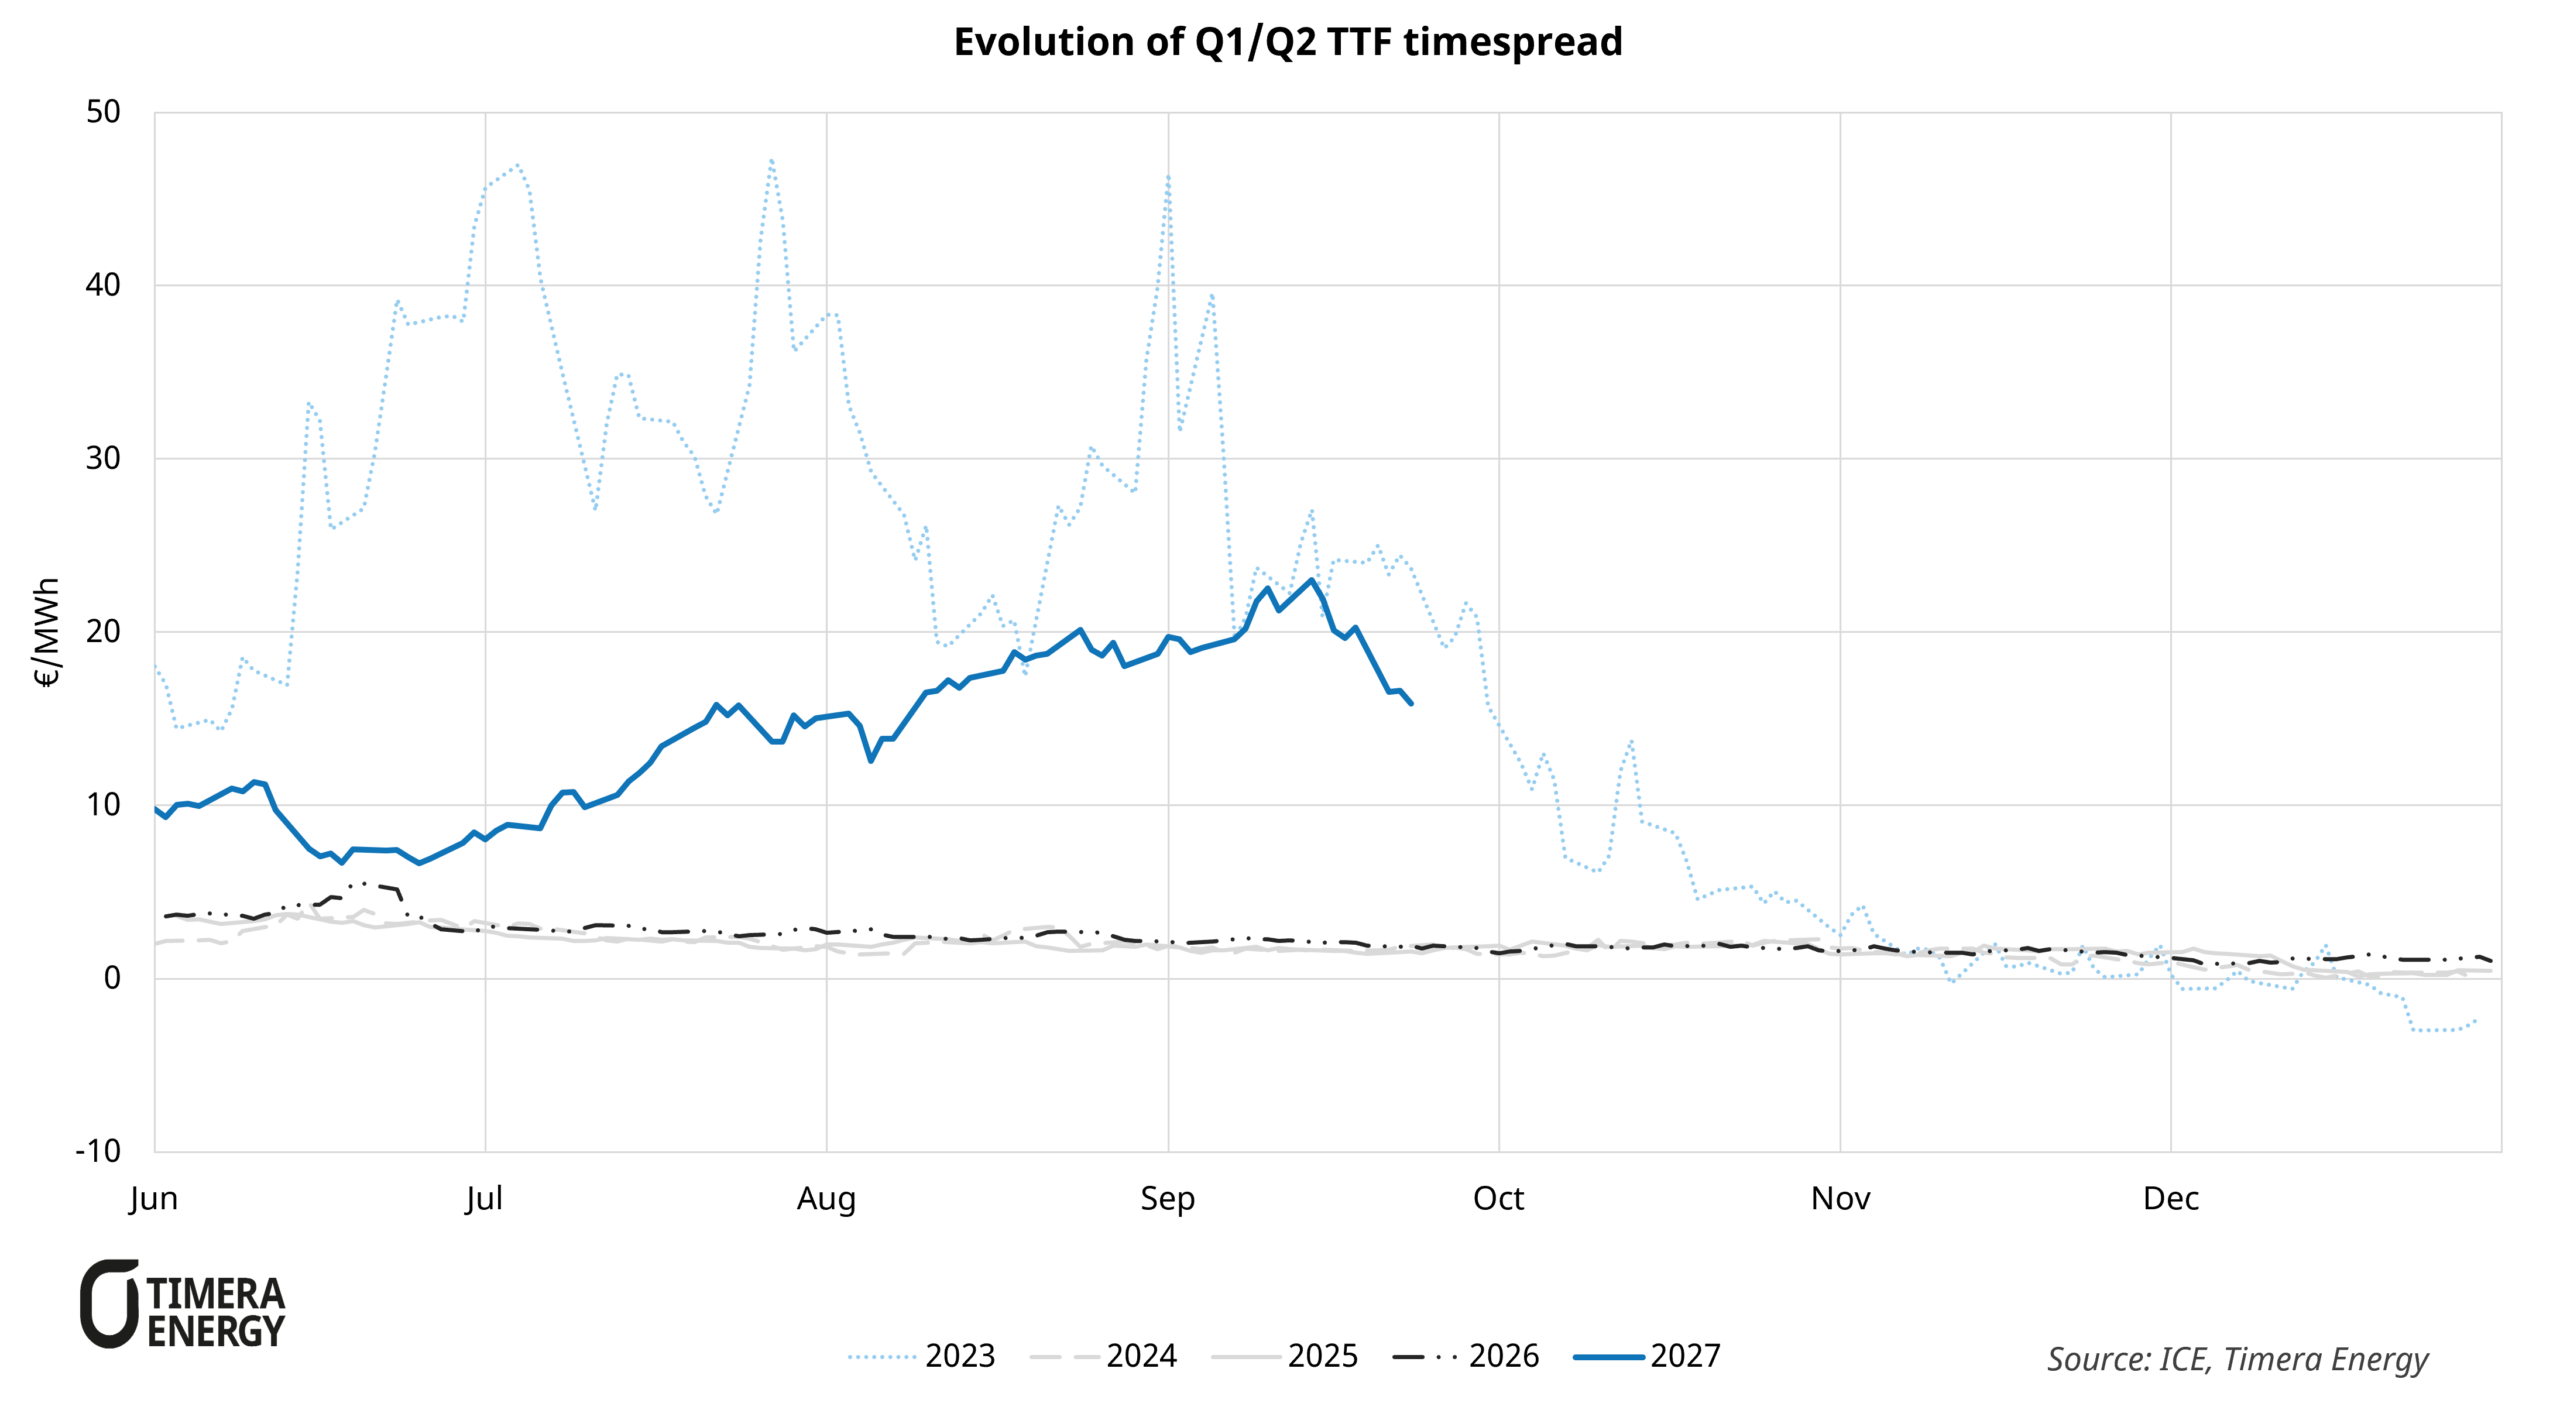
As flagged in our late Q2’26 outlook to subscribers, TTF Q1’27’s premium over Q2’27 has risen sharply through summer, from about €7/MWh in late June to a peak of about €23/MWh in mid-September, before easing to about €16/MWh.
This is the largest Q1 premium over Q2 since Oct-2022; when Europe was navigating the loss of Russian pipe supply. While thus not unparalleled, the depth of this backwardation is notable given absolute prices sit 66% below equivalent levels from 2023.
The curve is pricing two distinct phases. Q1’27 carries a significant risk premium given depleted European storage and the risk of continued disruption through the Strait of Hormuz. Q2’27, meanwhile, reflects the transition into an injection season that could see record year-on-year growth in global LNG supply, driven by new liquefaction capacity and a potential reopening of Hormuz.
We will publish our updated short-term outlook to Global Gas subscribers next week. To discuss the service or our outlook in more detail, contact Luke Cottell (luke.cottell@timera-energy.com).