Brent priced above $106/bbl on Monday (+4%), after drone attacks caused the suspension of the Saudi Arabia East-West pipeline late on Friday. Recent throughput has been ~5 mb/d (5% of global supply), and the pipeline is the only material route bypassing Hormuz.
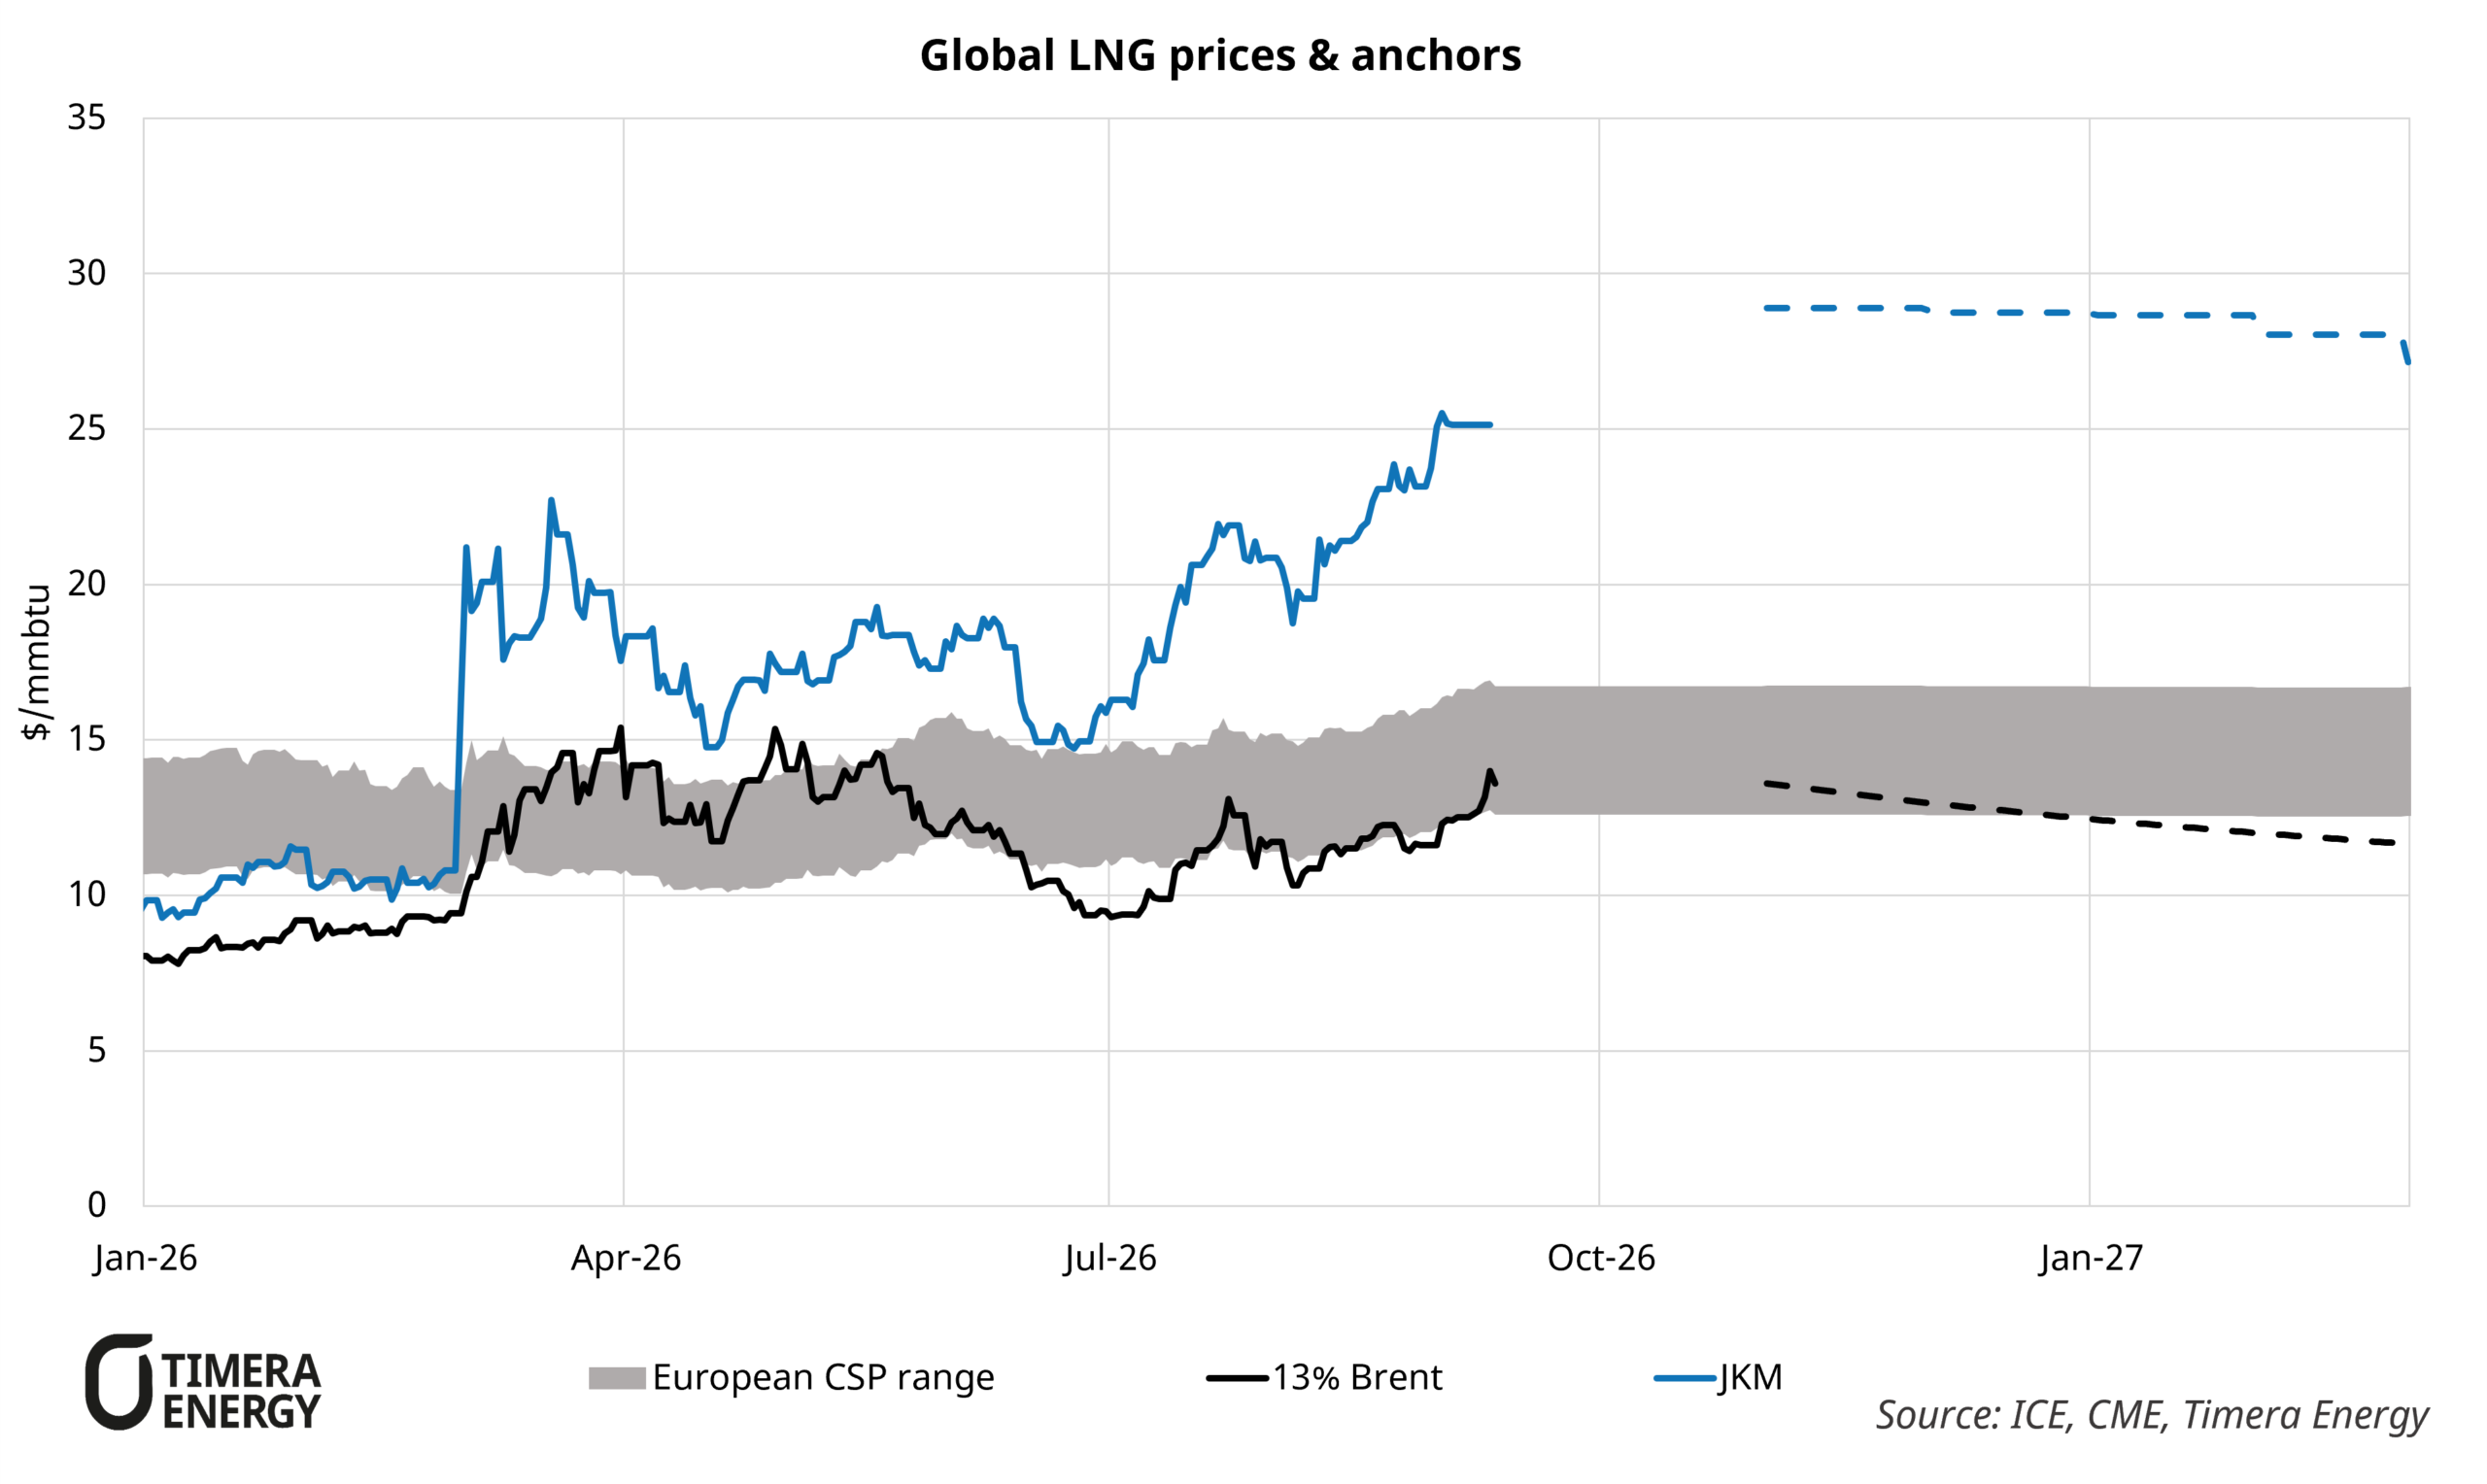
JKM has followed, with the November contract reaching $28/mmbtu, the highest JKM has traded since January 2023. Further upside risk remains into winter with storage levels at 68%, 20% lower than the five-year seasonal norm of 88% (see this week’s feature article for more on this).
The crisis has hit LNG harder than crude. Gas competes against refined products such as diesel and fuel oil in industry and transport sectors, and it is the product cracks that have jumped. Oil-indexed LNG contracts track Brent alone however, with spot LNG at a ~$14/mmbtu premium to a 13% Brent contract pricing around ~$14/mmbtu (equivalent to $53m on a standard cargo). In this environment, volume flexibility in contracts has become incredibly valuable.
Timera Energy will be publishing our Q3’26 Global Gas Update to subscribers at the end of September, including further analysis on LNG vs oil competition. Please reach out to Luke Cottell (luke.cottell@timera-energy.com) for a sample copy.